Quick Answer
ESI calculation in India is on gross monthly wages, not basic salary alone. The employee pays 0.75% and the employer pays 3.25%, so the total is 4%. For example, on ₹20,000 gross, the employee pays ₹150 and the employer ₹650.
ESI applies to employees earning up to ₹21,000 a month (₹25,000 for persons with disabilities). The contribution is due by the 15th of the next month.
ESI calculation in India is one of those payroll components that most HR managers understand in theory but get wrong in practice. Mostly people know that employee pays 0.75%, employer pays 3.25%. Total 4% of gross wages.
Might be you are thinking, if it’s that simple then where is goes wrong, friends it goes wrong in details. Like, who exactly is eligible? What counts as wages for ESI? What happens when an employee’s salary crosses ₹21,000 mid-year? What if your company has employees in both ESI-notified and non-notified areas?
I’ve seen payroll teams calculate ESI perfectly for 80% of employees – and completely miss the edge cases that come back as ESIC compliance notices six months later. This article covers everything. The formula, the eligibility rules, real calculation examples.
What is ESI Calculation and Who Must Register?
ESI stands for Employees’ State Insurance. It’s a social security scheme governed by the ESI Act 1948 and administered by ESIC – the Employees’ State Insurance Corporation under the Ministry of Labour and Employment.
The scheme provides medical care, sickness benefits, maternity benefits, disability allowance, and dependent benefits to eligible employees and their families. For many workers earning under ₹21,000 a month, this is their only real health coverage. It’s not a deduction to be minimized – it’s a benefit that matters.
Every factory with 10 or more workers, and every other establishment (office, shop, restaurant, cinema, hotel) with 10 or more employees in ESI-notified areas must register with ESIC. Once registered, the obligation is permanent – even if headcount later drops below 10.
Who is Eligible for ESI?
Eligibility is based on one number – the employee’s gross monthly wages.
Employees earning ₹21,000 per month or less are covered under ESI. For employees with disabilities, the threshold is ₹25,000 per month.
This ₹21,000 limit applies to gross wages – which includes basic salary, dearness allowance, HRA, conveyance, special allowance, and overtime. Essentially everything that appears on the payslip as an earning component.
What is excluded from the ESI wage calculation: employer’s contribution to PF, gratuity, reimbursements like travel bills and medical claims paid against actual expenses, and annual bonuses that are paid as part of a statutory obligation.
One rule that confuses many payroll teams – if an employee earning ₹19,000 gross gets a promotion mid-year and their salary moves to ₹23,000, do ESI deductions stop immediately? No. They continue until the end of the contribution period. ESI follows two contribution periods:
- April 1 to September 30 (contributions) → benefits from October 1 to March 31
- October 1 to March 31 (contributions) → benefits from April 1 to September 30
If a salary crosses ₹21,000 during a contribution period, ESI continues for the rest of that period. It stops only at the beginning of the next contribution period.
ESI Contribution Rates
The rates have been unchanged since July 1, 2019:
| Contributor | Rate |
| Employee | 0.75% of gross wages |
| Employer | 3.25% of gross wages |
| Total | 4% of gross wages |
One important exception: employees whose daily average wage is ₹176 or less are exempt from paying the employee’s 0.75% share. The employer still pays their 3.25% for these workers.
The ESI Calculation Formula
Employee ESI = 0.75% × Gross Monthly Wages
Employer ESI = 3.25% × Gross Monthly Wages
Total ESI = 4% × Gross Monthly Wages
Both amounts are rounded to the nearest rupee in practice, though technically calculated to two decimal places. Understand with Practical Calculation Examples
Example 1 – Standard Eligible Employee
Ramesh works as a production supervisor. His monthly salary:
- Basic: ₹12,000
- HRA: ₹4,800
- Conveyance: ₹1,600
- Special Allowance: ₹2,000
- Gross: ₹20,400
Since gross is below ₹21,000 – ESI applies.
Employee ESI = 0.75% × ₹20,400 = ₹153 Employer ESI = 3.25% × ₹20,400 = ₹663 Total monthly ESI contribution = ₹816
Ramesh’s take-home is reduced by ₹153. The company deposits ₹816 with ESIC.
Example 2 – Employee Near the Threshold
Sunita is a customer service executive earning:
- Basic: ₹13,000
- HRA: ₹5,200
- Special Allowance: ₹2,500
- Gross: ₹20,700
ESI applies.
Employee ESI = 0.75% × ₹20,700 = ₹155.25 → ₹155 Employer ESI = 3.25% × ₹20,700 = ₹672.75 → ₹673 Total = ₹828
Example 3 – Employee with Overtime
Vijay’s regular gross is ₹18,000. In October, he worked 20 hours of overtime – overtime pay of ₹2,500 was added to his salary.
Gross for October = ₹18,000 + ₹2,500 = ₹20,500
Overtime is included in ESI wages. ESI applies on ₹20,500.
Employee ESI = 0.75% × ₹20,500 = ₹154 Employer ESI = 3.25% × ₹20,500 = ₹666
Example 4 – Salary Crosses ₹21,000 Mid-Year
Priya’s gross was ₹19,500 from April to July. In August, she got a promotion – gross moved to ₹24,000.
April to September is one contribution period. Since Priya was enrolled in April at ₹19,500, ESI continues through September 30 – even though her August and September salary is above ₹21,000.
From October 1 (the new contribution period), ESI deductions stop.
This is the rule most payroll teams miss. And missing it means under-deducting for two months – which shows up as a discrepancy in the half-yearly ESIC return.
When Must Be ESI Deposited?
ESI contributions must be deposited with ESIC by the 15th of the following month.
April contributions → deposit by May 15. September contributions → deposit by October 15.
Late deposit attracts damages under Section 85B of the ESI Act – up to 25% of the contribution amount depending on the delay period. ESIC also has the power to recover dues as arrears of land revenue, which is more serious than a simple penalty.
Check also with: ESIC India →
Use the Runtime ESI Calculator
We’ve built a free ESI Calculator that does this instantly. Enter the employee’s gross wages and get the exact employee contribution, employer contribution, and total ESI amount – no formulas, no rounding guesswork.
👉 Use the Free ESI Calculator →
How Runtime HRMS Handles ESI Calculation
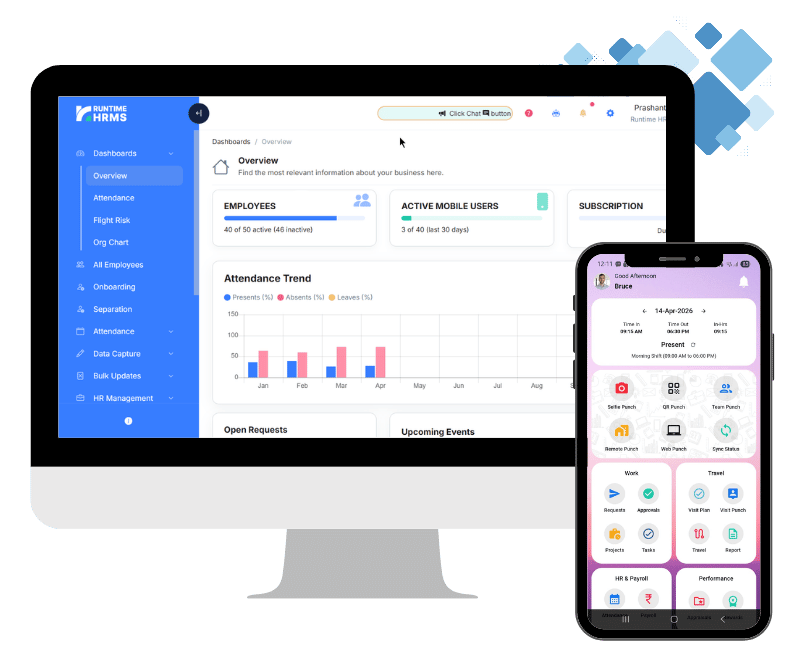
Doing ESI by hand means checking every employee against the ₹21,000 limit each month, then rebuilding the figures for the deposit. Runtime Payroll takes that work out of the month-end routine.
Statutory deductions sit in one place. ESI and PF are set up as statutory deductions, next to Professional Tax and TDS, in the same payroll run.
ESI is calculated with the salary. Runtime calculates salary, PF, ESI, Professional Tax and TDS from your attendance and leave data, so the ESI deduction is already on the payslip when payroll is finalised.
The monthly ESI file is generated for you. Runtime can generate the monthly contribution report as an Excel file for ESI filing, and you can upload that file on the ESI portal. You don’t have to rebuild the figures from the payroll sheet.
Payslips go out in one step. HR can send payslips in a single click, and employees can download them in the Workman app after payroll is finalised. Employees can then see their ESI deduction themselves and ask HR fewer questions.
Still calculating ESI by hand every month?
Runtime Payroll calculates ESI and PF with the salary, so deductions and challans match the payslip.
Sign Up TodayCommon ESI Mistakes HR Teams Make
Excluding HRA from the ESI wage base is the most frequent error. HRA is part of gross wages for ESI purposes – unlike PF, where HRA is excluded. Using the PF wage base for ESI gives you a lower ESI contribution than required.
Not tracking the contribution period boundary. When a salary crosses ₹21,000 mid-year, stopping ESI immediately rather than at the next contribution period boundary creates underpayment.
Ignoring ESI for contract workers. If your company deploys workers through contractors in ESI-notified areas – and those workers earn below ₹21,000 – the principal employer is responsible if the contractor hasn’t covered them. Don’t assume it’s the contractor’s problem alone.
Missing the ₹176 daily wage exemption for the employee’s share. Very low-wage workers are exempt from paying their 0.75% – but employers still pay 3.25%. Deducting from exempt workers is a compliance error.
Quick Summary
- ESI applies to employees earning ₹21,000 gross or less (₹25,000 for persons with disability)
- Employee contributes 0.75%, employer contributes 3.25% of gross wages
- Gross wages include basic, HRA, allowances, and overtime – not reimbursements or employer PF
- Employees earning daily average ≤ ₹176 are exempt from the employee’s 0.75% share
- When salary crosses ₹21,000 mid-period, ESI continues until end of that contribution period
- Deposit deadline: 15th of following month
- Half-yearly return deadline: 42 days after contribution period ends
- Principal employer is liable if contractor workers are not covered
FAQs
Is ESI calculated on basic salary or gross salary?
On gross monthly wages, which include basic, DA, HRA and other allowances. Employer PF, gratuity and reimbursements are not counted.
What is the ESI wage limit?
₹21,000 gross a month, and ₹25,000 for persons with disabilities.
What is the ESI contribution rate?
0.75% from the employee and 3.25% from the employer, 4% in total.
When must ESI be deposited?
By the 15th of the following month.